

Electronic payments give customers more ways to pay for your goods and services. In DHL’s 2026 E-Commerce Trends Report, 62% of online shoppers say they would abandon a purchase if their preferred payment method were unavailable. Only 45% of businesses identify this as a major cause of abandoned carts.
Electronic payments can speed up checkout and make remote purchases easier than cash or paper checks. Features such as encryption help protect payment details.
Learn how electronic payments work and which payment methods your ecommerce business can accept.
What is an electronic payment?
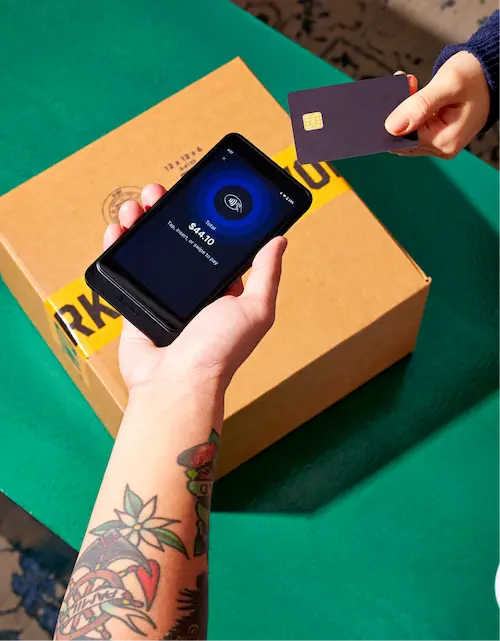
According to the Federal Deposit Insurance Commission (FDIC), an electronic payment is a transfer of money started through an electronic terminal, phone, or computer. For example, tapping a debit card at checkout authorizes a payment from your bank account.
Electronic payment options include:
- Credit card payments and debit card payments
- ACH transfers, including direct debits and e-checks
- Digital wallet payments
- Electronically initiated wire transfers
- Real-time payments through FedNow or RTP
- Buy now, pay later (BNPL), which lets shoppers repay purchases in installments
What is an electronic payment system?
An electronic payment system is the technology and rules used to process payments and transfer funds. Its payment rails are the underlying networks, such as ACH or card networks.
Digital wallets like Apple Pay and Google Pay, and checkout tools like Shop Pay, initiate payments over these rails. They aren’t payment rails themselves.
How does electronic payment processing work?
Electronic payment processing takes a transaction from the customer’s payment instruction through verification and settlement to the merchant’s receipt of funds.
The exact parties and sequence vary by payment method. For example, card payments involve card networks and issuing banks, while ACH debits need the account holder’s permission and can be returned after submission. Real-time bank payments settle almost immediately.
For a typical online card purchase, the process works like this:
- The customer submits payment details. Your checkout collects the customer’s card information or a wallet token. A payment gateway securely sends the payment request to your processor.
- The card issuer authorizes the payment. The payment processor routes the request through the card network to the bank that issued the card. That bank checks available funds or credit and approves or declines the transaction.
- You capture the payment. The system submits an approved transaction for payment. Depending on your settings, this happens automatically at checkout or later, such as when you ship the order.
- The payment clears and settles. The financial institutions exchange transaction details and calculate the amounts owed. Funds move from the issuing bank to the acquiring bank, which receives payments for your business.
- You receive a payout. Your payment provider sends the proceeds, less applicable fees and adjustments, to your payout account. Payout schedule determines when this happens. Bank processing can add time before you can spend the money.
For example, a customer buys a jacket from your online store using a debit card. Their bank approves the transaction after checking their available balance.
You capture the payment when you ship the jacket. After settlement, your provider includes the sale proceeds in a payout.
Shopify Payments lets you accept payments and track payouts in your Shopify admin. Eligible US businesses can receive those payouts in Shopify Balance, a money management account for business funds. Shopify Payments payouts can arrive there in as little as one business day from the transaction processing date, though timing varies.
Types of electronic payment methods
Electronic payment methods differ in cost, speed, and dispute rules. Some options overlap. For example, e-checks use ACH, and wallets and QR codes initiate payments through underlying networks.
This comparison reflects US business use. Your costs depend on your provider, account, and transaction type. Payment approval and access to the money can happen at different times.
| Method | Typical cost | Typical speed | Reversibility and dispute exposure | Best fit | Recurring billing |
|---|---|---|---|---|---|
| Credit cards | Percentage plus fixed fee. Shopify Basic’s standard online rate is 2.9% + 30¢. | Approval in seconds. Payout follows provider schedule. | Refunds and chargebacks. | Online and in-store purchases. | Yes, with customer authorization. |
| Debit cards | Processor’s debit rate; some providers charge the same flat rate as credit cards. | Approval in seconds. Merchant payout follows provider schedule. | Refunds and disputes under bank and network rules. | Purchases funded from a bank account. | Yes, with customer authorization. |
| Digital wallets | Underlying payment method’s fee. | Usually seconds for approval. | Underlying card or bank dispute rules apply. | Mobile and online checkout. | Depends on wallet and integration. |
| ACH transfers and direct debit | Flat or percentage fee. Stripe charges 0.8%, capped at $5, for ACH Direct Debit. | Same day to two business days on the network. | Returns and unauthorized debit disputes. | Payroll, invoices, and subscriptions. | Yes, through authorized debits or scheduled credits. |
| Electronic checks | ACH processing fees; provider charges vary. | Several business days, depending on provider. | ACH return and dispute rules apply. | Customers who prefer paying from a checking account. | Yes, with recurring authorization. |
| Wire transfers | Bank-set fees. | Usually the same business day domestically. | Difficult to recall after processing. | Large supplier payments and international transfers. | Scheduled transfers where offered. |
| Real-time payments | Bank or provider sets customer fees. | Seconds, including weekends and holidays. | Settled payments are final; a return request doesn’t guarantee recovery. | Urgent bank-to-bank payments. | Depends on bank scheduling and authorization features. |
| QR code payments | Underlying payment method’s fee. | Follows underlying payment method. | Follows underlying payment method. | Mobile checkout at markets, counters, or tables. | Depends on the payment service opened by the code. |
| Peer-to-peer apps | Business transaction fees vary. Venmo charges 1.9% + 10¢ for direct payments to business profiles. | Often immediate in the app. | App-specific purchase disputes and funding reversals. | Small sales through an approved business account. | App-dependent. |
| Buy now, pay later (BNPL) | Percentage plus fixed fee. | Payout follows provider schedule. | Provider dispute rules apply. | Purchases customers want to repay in installments. | Provider-dependent. |
| Crypto | Network and provider fees vary. | Depends on blockchain confirmation and provider payout timing. | Blockchain transfers generally aren’t reversible. | Customers paying from crypto wallets. | Available through some providers, including stablecoin subscriptions. |
1. Credit and debit cards
Credit cards let customers borrow from a card issuer and repay the balance later. Debit cards draw money from a linked bank account. Businesses can accept both card types online and at payment terminals, with proceeds paid out through their processor.
Pros
- Fast payment approval lets customers complete purchases at checkout.
- Saved card details make repeat purchases and authorized subscription payments easier.
Cons
- Processing fees apply to both card types. Chargebacks can reduce merchant payouts.
- For customers, unpaid credit card balances can accrue interest. Debit payments can trigger overdraft fees, depending on the account.
2. ACH transfers and direct debit
ACH transfers move money between US bank accounts through the Automated Clearing House network. An ACH credit pushes funds from the payer’s account. An ACH debit, also called direct debit, lets the payee collect funds with the account holder’s permission.
An online bank transfer describes how someone initiates a payment. ACH identifies the network that carries it. A transfer submitted through online banking can use ACH or another network.
Eligible US stores using Shopify Payments can offer ACH Direct Debit for B2B orders. Customers authenticate a United States bank account and pay in USD.
Pros
- Fees are often lower than card processing fees, especially for larger payments.
- Authorized recurring debits automate collections for regular invoices or subscriptions.
Cons
- Confirmation takes longer than card approval. Shopify ACH Direct Debit payments can take up to four business days to process.
- Insufficient funds and customer disputes can result in returned payments and additional fees.
3. Electronic checks (e-checks)
An electronic check is a payment authorized using a customer’s bank account and routing details. In US payment processing, e-checks generally travel through ACH as direct debits. They use the same network as other ACH payments.
Pros
- Electronic submission removes the need to mail and deposit a paper check.
- Processing fees are often lower than card fees.
Cons
- Payment confirmation can take several business days.
- Incorrect account details or insufficient funds can cause returns. Customers can also dispute unauthorized debits.
4. Digital wallets and contactless payments
Digital wallets store payment credentials and pass them securely to a payment processor. Apple Pay and Google Pay let customers use saved payment methods online and at compatible contactless terminals. Shop Pay saves payment and delivery details for faster checkout.
These services use underlying payment rails, such as card networks. Contactless payments also work with physical cards that customers tap against a reader.
According to Worldpay’s 2026 Global Payments Report, digital wallets accounted for 40% of US ecommerce transaction value in 2025, compared with 32% for direct credit card payments. A wallet purchase can still be funded by a credit card.
Pros
- Saved details and tap-to-pay reduce the steps customers take to complete a purchase.
- Services such as Apple Pay use payment tokens to protect the customer’s actual card number.
Cons
- Acceptance depends on compatible checkout software or contactless hardware.
- Processing fees and the underlying payment method’s dispute rules still apply.
5. Wire transfers
Wire transfers move money between bank accounts through wire payment systems. International transfers can pass through intermediary banks before reaching the recipient. Fees, cutoffs, and transfer limits depend on the banks involved.
Pros
- Domestic wires often arrive the same business day when submitted before the bank’s cutoff.
- Businesses can use wires for large supplier payments and international purchases.
Cons
- Sending and receiving fees add to the cost. International transfers can also involve intermediary charges and currency conversion markups.
- Money sent to an incorrect or fraudulent account can be difficult to recover after processing.
Which electronic payment methods are the most secure?
Payment security depends on preventing fraud and recovering money after a problem. Tokenized wallets can reduce exposure of card details. Wire transfers offer fast settlement, but money sent to a scammer can be difficult to recover.
Fraud costs businesses more than the amount stolen. A 2025 LexisNexis Risk Solutions study found that US merchants incur an average of $4.61 in total costs for every $1 of fraud. Across all fraud categories, people reported about $16 billion in losses to the FTC in 2025. That was the highest amount on record and about 25% above 2024.
For cards and wallets, encryption scrambles sensitive payment data. Payment tokenization replaces card numbers with substitute values, reducing exposure of the original details. Authentication checks who is making the payment.
The table below shows how each electronic payment method addresses risk.
| Payment method | Relevant protections | Risks to evaluate |
|---|---|---|
| Credit and debit cards | Encryption and tokenization protect card details. 3D Secure helps authenticate online customers. | Stolen credentials can lead to fraudulent purchases. Chargebacks give customers a dispute process but can cost merchants the sale amount and additional fees. |
| Digital wallets | Services such as Apple Pay combine tokenized card details with device authentication, such as a fingerprint or passcode. | Fraudsters can target accounts or persuade legitimate users to approve payments. Card-funded wallet purchases still follow applicable card dispute rules. |
| ACH direct debit and e-checks | Bank account verification and customer authorization help prevent unauthorized collections. | Verification doesn’t guarantee payment. Insufficient funds and unauthorized debit disputes can result in returns after submission. |
| Wire transfers and real-time payments | Bank authentication and transaction checks protect access to the sending account. | A legitimate account holder can still authorize a payment to a scammer. Recovery is difficult after processing, making recipient verification especially important. |
| BNPL and peer-to-peer apps | Providers offer different identity checks and fraud controls. Some transactions qualify for purchase protection. | Coverage depends on the provider and transaction type. Check who bears losses from fraud, customer disputes, and failed repayments. |
| Crypto | Cryptographic signatures authorize blockchain transfers. | Stolen wallet credentials and incorrect recipient addresses can cause losses. Payments are typically irreversible, and refunds usually depend on the recipient returning funds. |
For an unfamiliar online customer, review authentication results and fraud alerts before fulfillment. Before wiring money to a supplier with changed bank details, confirm those details using a phone number already on file.
For card acceptance, the Payment Card Industry Data Security Standard (PCI DSS) sets rules for protecting account data. Outsourcing processing can reduce your compliance workload, but merchants still have responsibilities, including checking their provider’s compliance.
What to look for in a provider:
- Data protection. Encryption and tokenization, plus documented PCI DSS compliance for applicable services.
- Authentication. Customer verification tools and multifactor authentication for staff accounts.
- Fraud controls. Alerts and adjustable rules for reviewing suspicious transactions.
- Dispute assistance. Deadlines, evidence submission tools, and written terms explaining liability and fees.
This article provides general information, not legal advice. Payment protections vary by jurisdiction, account type, and provider. Consult a qualified attorney about your business’s obligations.
How to choose payment methods for your online store
Build your payment mix around how customers shop and how your business gets paid.
Use these factors to decide which payment methods to offer:
- Understand customer preferences. Review payment use and checkout completion by device and market. Ask customers which options they want. For example, frequent mobile shoppers could benefit from a digital wallet that saves them from entering card details.
- Compare the total cost. Calculate processing costs for a typical order, including fixed fees and percentage charges. Fixed fees take a larger share of smaller purchases. Check refund, dispute, and currency conversion fees separately.
- Check when funds arrive. Compare the time from payment to usable funds in your account. An approval at checkout doesn’t mean the money is available to spend. Review payout schedules and possible holds against your supplier payment deadlines.
- Evaluate security and fraud exposure. Look for tokenization and customer authentication, plus tools to review suspicious orders. For card payments, check the provider’s PCI DSS compliance and your own responsibilities. Read the terms explaining who bears losses from fraud and chargebacks.
- Confirm geographic availability. Check whether each provider accepts businesses in your country and serves customers in your target markets. Verify accepted currencies and payout arrangements. A familiar local payment method can make checkout easier for customers abroad.
- Test the fit with your business. A subscription store needs payment methods that allow authorized recurring charges. A wholesale store could benefit from bank payments for larger invoices. Test the checkout process on mobile and desktop, including what customers see when a payment fails.
Shopify Payments is Shopify’s own payment provider and integrates directly with your store’s checkout. Eligible businesses can manage payment settings and review fees and payouts in the Shopify admin. Available payment methods depend on your store’s location and other eligibility criteria.
Read more
- Order-to-Cash Process: A Step-by-Step Guide
- Contribution Margin vs. Gross Margin: Key Differences
- What Is Last In First Out (LIFO)? Definition and Guide
- What Is a Product Life Cycle? Definition and Guide
- What Is Gross Profit? Definition and Guide
- What Is Acid-Test Ratio? Definition and Guide
- What Is a Financial Statement? Definition and Guide
- What Is a Fiscal Year? Definition and Guide
- 5 Best Insurance Companies for Small Businesses
- Incremental Cash Flow Definition and Formula for Calculating
Electronic payment FAQ
What are electronic payments called?
Electronic payments are commonly called digital payments or e-payments. Electronic funds transfer (EFT) is a related term for money transferred electronically between accounts. ACH transfers are one type of EFT payment, with ACH referring to the specific network used to move the money.
What is an example of an electronic payment?
Paying for an online order with a debit card is an electronic payment. The customer’s bank approves or declines the payment request sent through your processor. After approval and processing, the provider sends the sale proceeds to a payout account according to its schedule.
Is it easy to set up electronic payments?
Yes, many ecommerce platforms offer built-in payment setup. Eligible Shopify businesses can activate Shopify Payments from their admin, provide business details, and add a payout account. Setup time depends on verification and the payment methods selected, so check your provider’s requirements before launch.
What is the safest form of electronic payment?
No electronic payment method is safest for every transaction. Wallets such as Apple Pay use tokenization and authentication to protect card details and verify the payer. Compare these protections with dispute rights and recovery options, since an authorized payment can still send money to a scammer.
Which type of electronic payment is typically favored in B2B?
ACH transfers are a common choice for US B2B payments, particularly recurring invoices and larger orders. Processing fees are often lower than card fees, though payment confirmation can take longer. Eligible Shopify merchants can offer ACH Direct Debit to B2B customers paying in USD from a United States bank account.